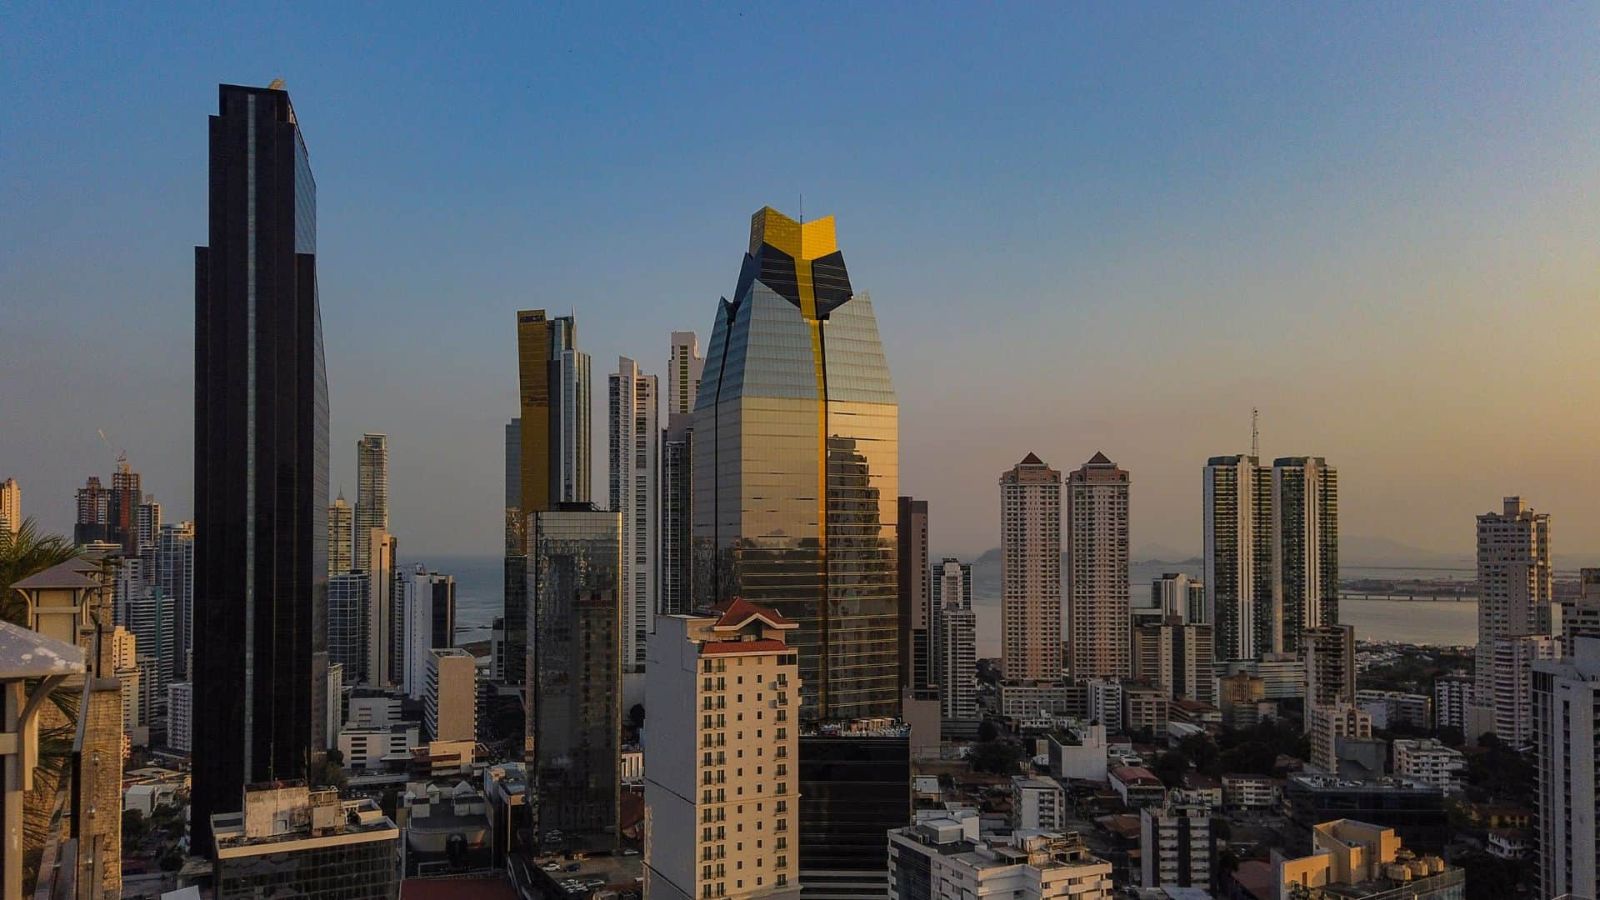
Panama has been on the radar of foreign investors for years, for one simple reason: it's one of the few dollarized economies in the region, with a Foreign Investment Law that gives foreign buyers the same property rights as a Panamanian. That doesn't mean investing here is automatic or risk-free — it means that with the right guidance, the risk is manageable.
This guide covers the real route: what to check before committing capital, how a purchase is structured, and the most common mistakes we see buyers make when they show up without a local Sherpa.
1. Start with due diligence, not the property
The most common mistake is falling in love with a property before confirming it makes sense on paper. Before signing any promise of purchase-sale, three things should always be checked:
- A clean title. Confirm at the Public Registry that the seller is in fact the owner and that the property carries no liens, mortgages, or pending litigation.
- Zoning and land use. What you see today isn't always what you can build or modify tomorrow — especially in coastal or conservation zones.
- Real market data. Not the asking price, but recent comparables in the area. A good advisor gives you this before you negotiate, not after.
"It's not just about the commission. It's about being a guardian of our client's investment." — that's how we understand advisory at Proper Consulting.
2. Understand the purchase structure before you negotiate
In Panama, it's common to buy property personally or through a Panamanian corporation, each with different implications for liability, succession, and in some cases taxation. The right structure depends on whether it's a home for personal use, an income-producing investment, or part of a larger portfolio — there's no single right answer, and anyone who gives you one without knowing your case is selling you a template, not advice.
3. The process, in broad strokes
While every transaction has its own particulars, most purchases follow a similar sequence:
- Promise of purchase-sale with an escrow deposit.
- Legal and technical due diligence during the agreed period.
- Signing of the public deed before a notary.
- Registration at the Public Registry in the buyer's name.
Exact timelines and requirements shift depending on whether the property is under horizontal property regime, a rural estate, or involves local financing — which is why we'd rather confirm the details with you case by case than hand you generic numbers that can go stale.
4. Financing: options to consider
Some Panamanian banks offer financing to foreigners, though the requirements (down payment, credit history, demonstrable income) are stricter than for a resident. Many investors choose to pay in cash or finance from their home country instead. The best route depends on your financial profile — it's one of the first things we review on a consulting call.
5. Common mistakes we see (and how to avoid them)
- Negotiating without comparables. Overpaying because there was no way to know the fair price for the area.
- Skipping due diligence because of time pressure. A "once-in-a-lifetime opportunity" that vanishes if you don't sign today almost never is.
- Not vetting the developer. On pre-sale projects, the developer's track record and solvency matter as much as the project itself.
- Assuming your home country's rules apply here. From taxes to closing timelines, Panama has its own framework — and it's worth confirming before assuming anything.
The bottom line
Investing in real estate in Panama can be one of the most profitable decisions you make — or an expensive lesson, depending on how well informed you go in. The difference almost always comes down to having someone on your side who knows the terrain and has no hidden interest in which property you choose.